Case Studies Alcohol Campari Group
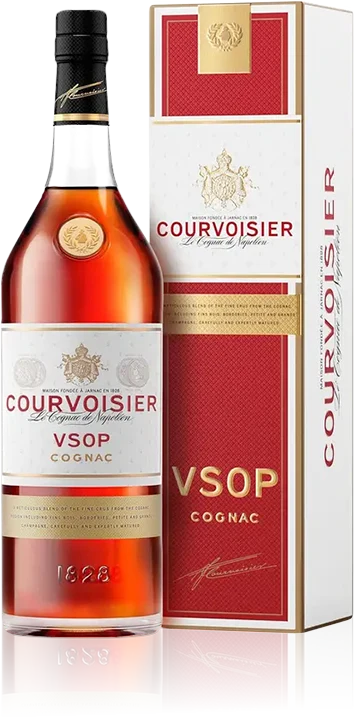
Courvoisier holds 20% of Cognac space in the UK. In Paris, it holds just 5%.
We benchmarked the brand’s share of Cognac & Brandy space across 19 UK and European airport stores — and pinned the loss to one airport, where every competitor had a branded fixture and Courvoisier had four listings.
- Client
- Campari Group
- Category
- Cognac & Brandy
- Scope
- 19 European airport stores
- Data
- Shelftrak audit, Aug 2024
The brief
Benchmark the brand against Europe. Then find the stores dragging it down.
Campari Group wanted to know whether Courvoisier was getting its fair share of Cognac & Brandy space in every store that matters, using total Europe as the benchmark.
Answering it meant measuring share of space, facings, listings and positioning against Hennessy, Martell and Rémy Martin — location by location.
Shelftrak audited eight UK stores and eleven across Europe. The UK was healthy. Across Europe, Courvoisier’s position was weaker — with Paris standing out in particular.
What the audit found
0%
lower share of Cognac & Brandy space in Europe than Courvoisier holds in the UK
0%
below the European average share of space across Paris CDG
0%
fewer facings per SKU than the other key Cognac brands in CDG T1
Finding 01
The UK sets the standard.
At a total level, Courvoisier commands 20% of Cognac & Brandy linear space in UK stores against 13% across Europe. The UK number proves the brand can hold a fifth of the category — which makes every European location below it a measurable opportunity.
Finding 02
At home, two Heathrow terminals need attention.
Gatwick and LHR T2 hold Courvoisier well above its national average. LHR T3 and T5 sit at half of it. Stansted and Manchester are also below the line, but their passenger mix means a lower share is expected there — so the conversation starts at Heathrow.
* Brand is multi-located in LGW North · = flagged for review
Finding 03
In Europe, Paris is the outlier — in both key stores.
Frankfurt T1 shows what good looks like. Frankfurt T2 and both Charles de Gaulle stores sit far below the European average, with CDG T1 at 3%. This is where the audit went deeper.
= stores flagged for review: Frankfurt T2 and both Paris CDG stores
Inside the store — Paris CDG T1
Four listings. No branded fixture. 5% of the category.
Cognac & Brandy holds more than 9% of the main store’s category space, and Hennessy owns 40% of it. Martell and Rémy Martin each hold three times Courvoisier’s share — and every one of them has a branded fixture. Courvoisier sits on an open shelf.
The range tells the same story: four unique Courvoisier SKUs against twenty-two for Hennessy. This is the evidence that turns “we should have more space” into a specific, photographed and measured retailer conversation.
Shelftrak audit photos — Paris CDG T1 main store
The recommendations
What the audit told Campari Group to do next
01
Close the gap to the European average
Courvoisier holds 13% of Cognac & Brandy space across Europe but far less in its weakest stores. Moving key locations towards the brand’s own average is the fastest space gain available.
02
Rebuild the position in Paris CDG T1
Five per cent of the category, four listings, no branded fixture. The audit gives Campari Group the evidence to reset Courvoisier’s competitive position against Hennessy, Martell and Rémy Martin.
03
Lead the Cognac & Brandy category review
Cognac & Brandy is more than 9% of the store’s category space. The data supports Campari Group advising Lagardère on a full category development plan — with Courvoisier at the centre.
Take this case study with you
The full Courvoisier Europe study as a PDF — charts, audit photos and findings. PDF · 1.9 MB
More case studies
All case studies →
Lorem ipsum dolor sit amet, minim molestie argumentum est at torquatos.
Apeirian detraxit pri eu. No solum accusam has. Ius ne harum mundi clita, eu pro tation audiam.